Most fitness policies do not name adaptive athletes at all, which is precisely the problem. Where a policy is silent, an owner cannot assume coverage…
Read MoreCategory: Gym Insurance
Participant accident insurance pays defined medical costs when someone is injured taking part in your activity, on a no-fault basis, without anyone having…
Read More
Possibly yes. Calling an instructor an independent contractor does not by itself remove your workers’ compensation obligation.
Read More
Yes, and the difference is one of the more expensive misunderstandings NEXO Insurance Services encounters. A general business owner’s policy is built for a…
Read More
No. A waiver and insurance do different jobs, and a waiver cannot replace coverage. A signed liability waiver is evidence that a member understood and…
Read More
Workers comp for independent contractors starts with a simple rule: your gym usually doesn’t have to cover true independent contractors under its workers’ comp policy. The catch is the word “true.” If a coach you pay as a contractor is really an employee under your state’s rules, your gym can owe workers’ comp for them […]
Read More
Personal trainer insurance cost depends on where you train, who you train, how you train and how much coverage you buy. For most independent trainers it’s affordable, usually far less than a single claim would cost to defend. The price moves with in-home and outdoor sessions, online clients, small groups, specialties like boxing or prenatal […]
Read More
Spin instructor insurance protects you when a rider gets hurt in your class and blames your setup, your cues or your intensity. Most indoor cycling instructors need general liability and professional liability, and many studios won’t put you on the schedule without a certificate showing both. If you teach at more than one studio, you […]
Read More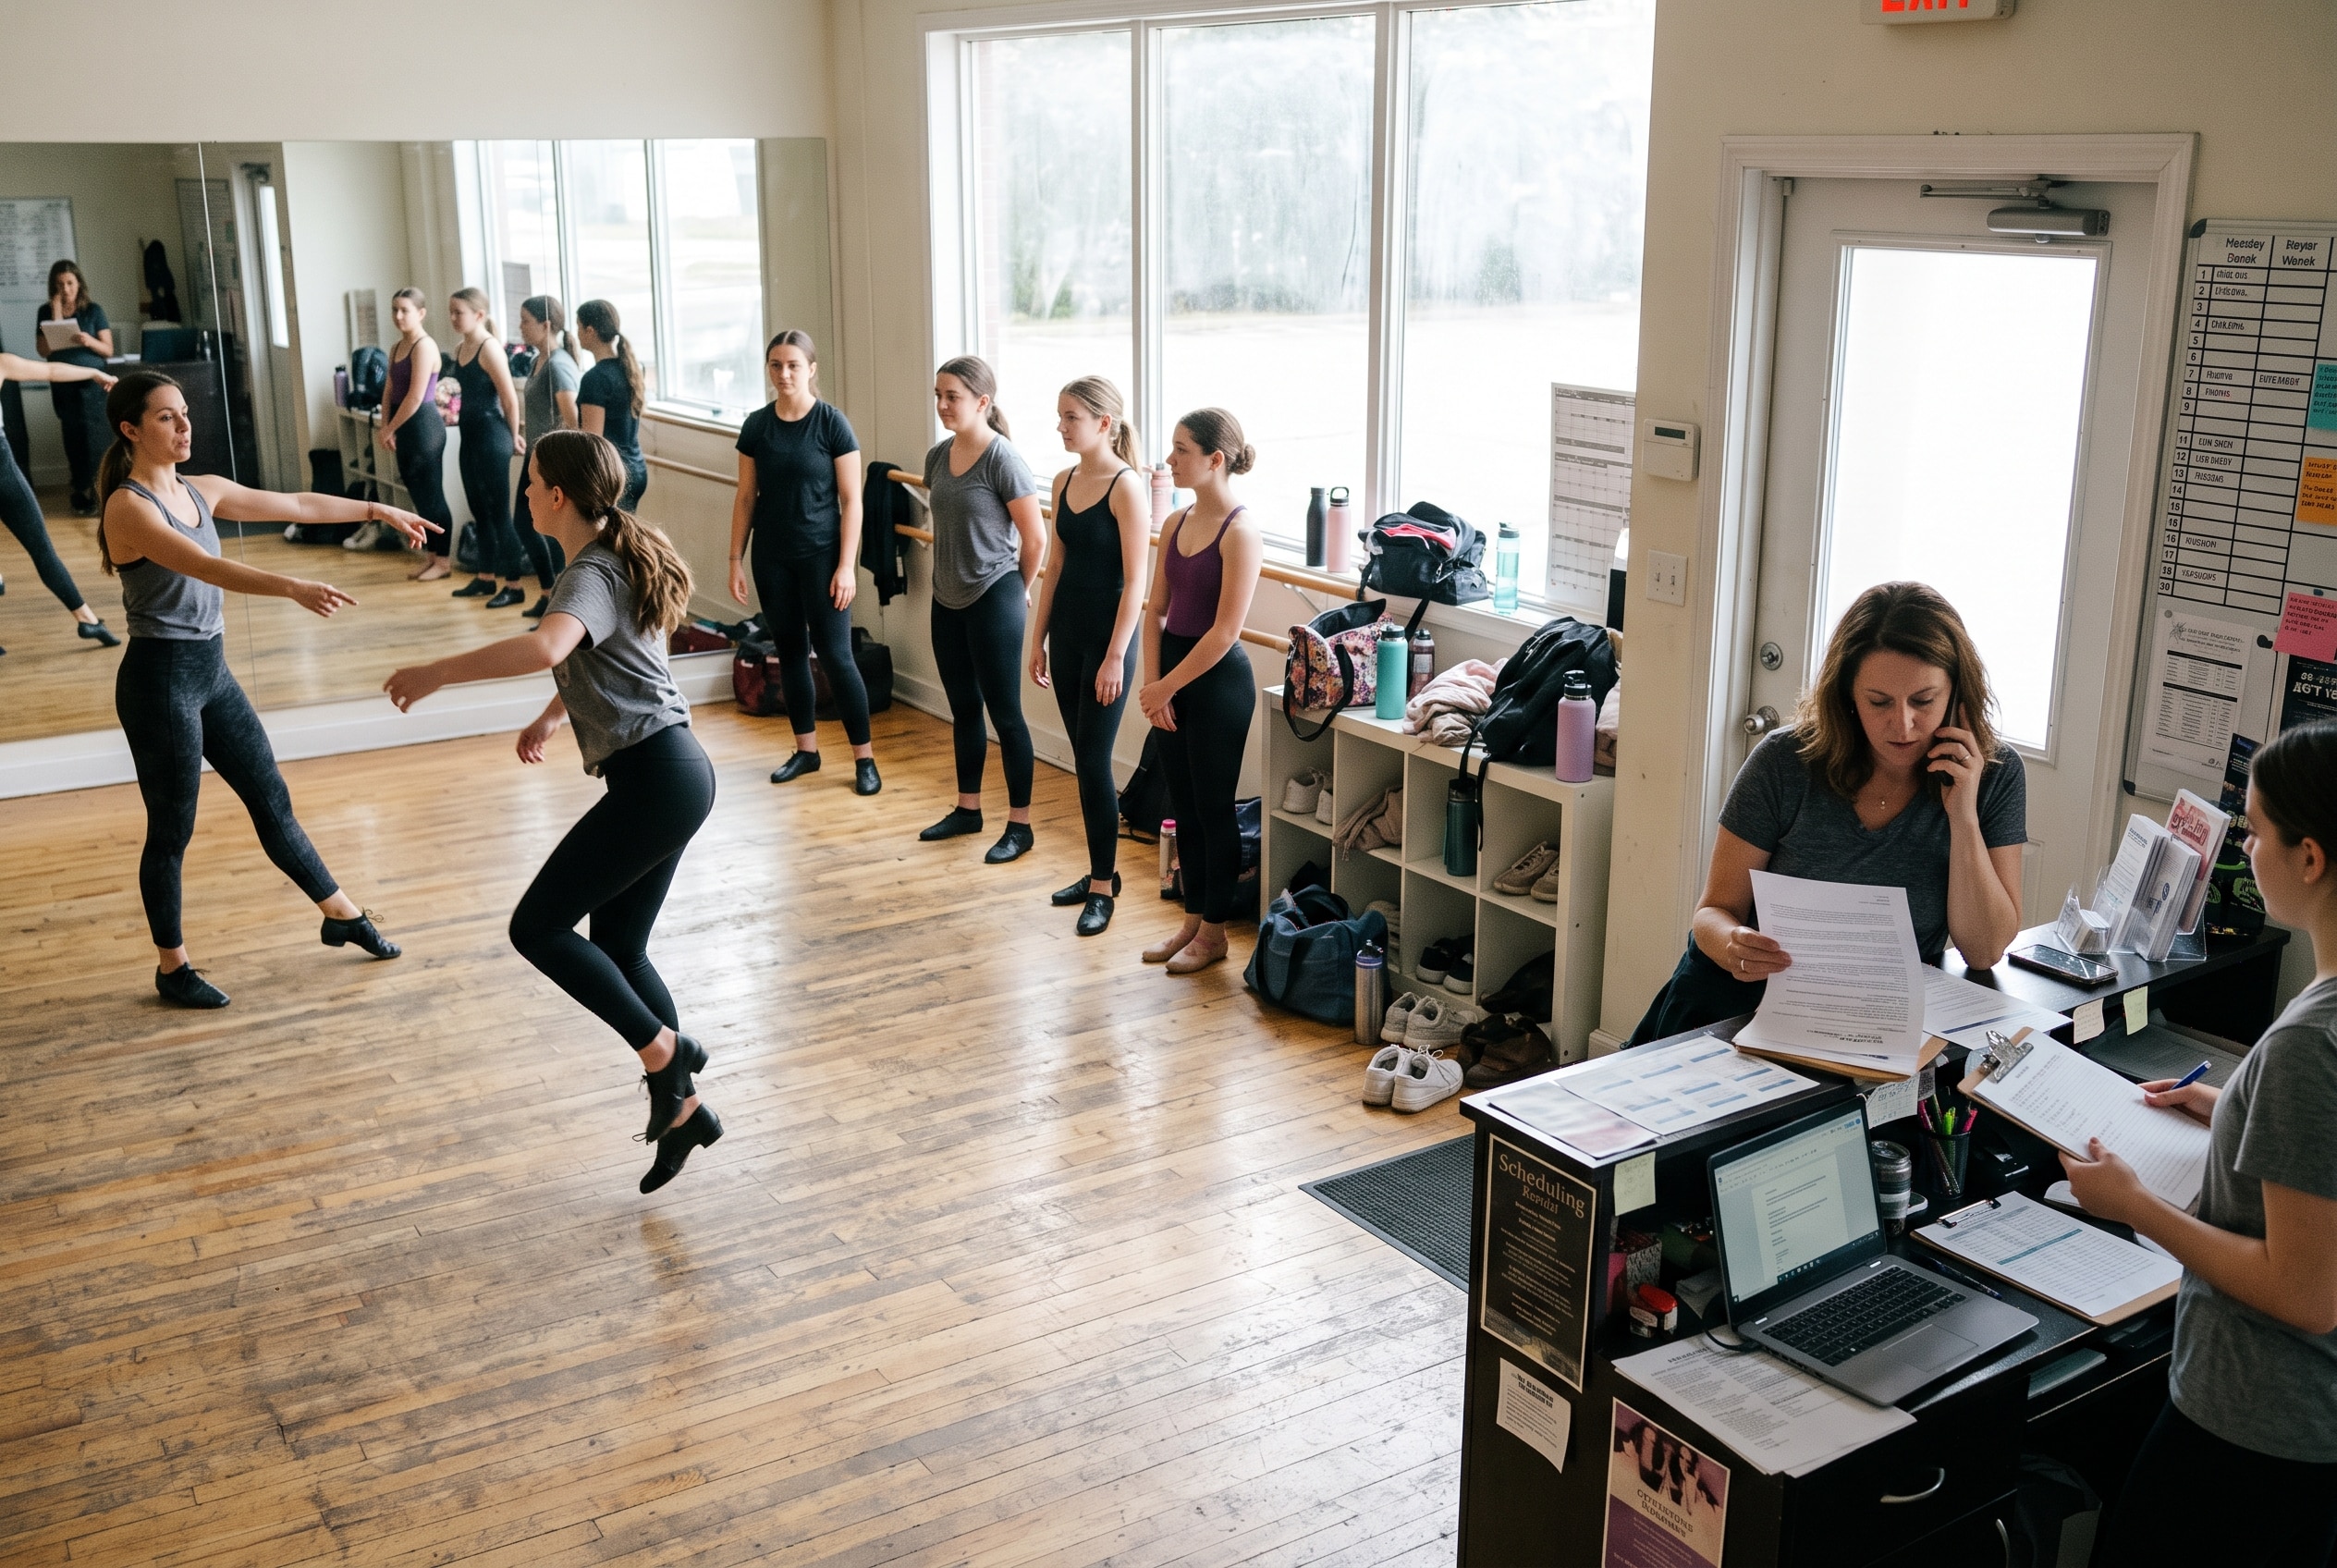
Dance Studio Insurance: The Risks Owners Miss and What Covers Them Dance studio insurance protects your business when a student gets hurt, a parent files a claim, equipment is damaged or an event goes wrong. Most studio owners buy a policy when they open and don’t look at it again. But a studio changes every […]
Read More
Employment practices liability insurance (EPLI) pays to defend your business when a current, former or prospective employee claims you broke employment law, like firing them unfairly, harassing them, or discriminating against them. It usually covers your legal defense plus settlements or judgments. General liability and workers’ comp don’t cover these claims, so without EPLI the […]
Read More