Gym & Fitness Studio Insurance: The Complete Owner’s Guide

What Core Coverages Do Gyms and Fitness Studios Require?

Running a gym is not like running a typical store. Members move around, lift weights, and take classes. They don’t just browse shelves. Because of this, gyms need more than basic general liability insurance. They need several types of coverage working together to close the gaps a normal policy leaves open. Each type of coverage protects a different part of the business, from injuries to payroll to computer data. Owners who understand each coverage type can catch a gap before it turns into a costly claim.

Commercial General Liability & Participant Injury

General liability insurance covers injury and property damage claims from members, guests, and visitors. But many standard policies don’t cover injuries that happen during workouts or classes. This is a big problem for gyms that offer group training. NEXO’s policies fix this by including participant injury coverage from the start, with no extra add-on needed.

Without this coverage, a lawsuit over a training injury might not be covered at all. Ask your agent in writing whether your policy covers participant injuries or whether it’s sold separately. That answer matters a lot when a claim comes in.

Professional Liability for Personal Trainers & Instructors

Professional liability insurance, also called errors and omissions (E&O) coverage, protects against claims that a trainer gave bad advice or poor supervision. NEXO’s policies cover employees and staff, but independent contractors (1099 workers) usually need their own coverage.

If a member says a trainer gave them an unsafe exercise, that’s a professional liability claim, not a basic injury claim. These are handled differently. Gyms that rely heavily on contractors face greater risk here, since a contractor’s mistake can still come back on the business. Always require contractors to carry their own insurance and list your gym as an additional insured before they teach.

Commercial Property & Specialized Fitness Equipment Protection

Property insurance covers the physical stuff that keeps a gym running: flooring, mirrors, weights, cardio machines, and HVAC systems. NEXO offers a policy built for gym equipment, covering damage from fire, water, and theft. Regular commercial policies often treat gym flooring and mirrors as basic upgrades, which can result in underpayment after a claim.

Replacing commercial flooring and equipment costs more than many owners expect. Get an accurate estimate of your value when you set up your policy so you’re not underinsured.

Business Interruption & Loss of Income

Business interruption insurance replaces lost income, payroll, and rent if you have to close due to property damage. If a pipe bursts and floods your gym for two weeks, you still owe rent and still have to pay staff, even with no members coming in. This coverage keeps a short-term problem from becoming a long-term financial disaster.

Insurers look at your past revenue and regular costs, like rent and utilities, to calculate your payout. Keeping clean financial records helps speed up the claims process.

Workers' Compensation & Payroll Tax Integration

Workers’ compensation covers medical costs and lost wages when an employee gets hurt on the job. Trainers, instructors, and maintenance workers all face physical risks daily, so this coverage is required in almost every state. NEXO offers workers’ comp in 46 states, excluding Hawaii, North Dakota, Ohio, and Wyoming. It also comes bundled with payroll tax filing, which reduces paperwork.

Gyms expanding into new states should check workers’ comp rules early, since requirements differ by state.

Cyber Liability & Member Data Protection

Gyms rely on digital systems for billing, check-ins, and scheduling, and these systems all hold member data. Cyber liability insurance covers costs after a data breach, including investigation, system repairs, and notifying members. A single ransomware attack could expose thousands of payment records in hours.

This risk keeps growing as more gyms move to app-based memberships and unstaffed entry. It’s especially important for gyms that store card data themselves instead of using a third-party processor. Cyber coverage should be a priority, not an afterthought.

Real-World Claim Scenarios: How Coverage Responds in Practice

It’s one thing to read a policy summary. The value becomes much clearer when you see how coverage responds in a real incident. Below are typical situations gym and studio owners experience and how a properly written policy addresses each one.

Scenario 1:
Member Achilles Rupture During Box Jumps

Member tears Achilles tendon during high-intensity group class. Then the member sues the studio, alleging the exercise was inappropriate for their fitness level. Many standard general liability policies exclude this type of athletic injury altogether. This means the business has to pay for its own legal defense costs and any settlement. NEXO’s core policy includes participant injury coverage. Instead of paying out of pocket for this type of claim, the policy covers legal defense and medical settlement costs.

Scenario 2:
Cable Cross Tower Collapse & Traumatic Injury

During use, a cable fitting on a cross tower machine breaks off and strikes a member, resulting in cuts to the face and dental damage. NEXO aligns medical expense limits with general liability defense. It also simultaneously tests whether the equipment manufacturer is partly responsible. That review can lead to a claim by the manufacturer, which protects the gym owner from full financial responsibility for a defective product.

Scenario 3:
Burst Pipe Destroys Sprung Wood & Rubber Flooring

An overnight plumbing failure flooded the facility, destroying 3,000 square feet of custom rubber flooring and the subfloor beneath it. The studio has to be closed for two weeks. NEXO files a property insurance claim to cover the reconstruction of the structure. Business interruption coverage also replaces lost member revenue during the closure. Without both coverages working together, the studio would have to pay the repair bill and the lost income at once.

Scenario 4:
Trainer Sexual Misconduct Allegation

A one-on-one stretching session with a trainer results in a member suing for inappropriate physical contact. NEXO has abuse and molestation coverage with legal defense and settlement coverage in such claims. That coverage is bundled with background checks at $19.50 per candidate to ensure compliance with hiring requirements before issues arise. Facilities offering hands-on training or youth programs face higher exposure here. Think of this coverage as a baseline rule and not an optional add-on.

Scenario 5:
Group Fitness Instructor Back Injury

A lead instructor blows out a disc during a live class while demonstrating a deadlift. This is an employee workplace injury, so the claim is processed through NEXO’s workers’ compensation program. That includes coverage for medical treatment, temporary disability pay, and physical therapy within its 46-state footprint. This illustrates why workers’ compensation remains important even for physically active employees.

Scenario 6:
Outdoor Boot Camp Member Heat Stroke

A member suffers from severe heat exhaustion during an off-site summer workout at a public park and collapses. The member then sues the studio for negligent conduct. NEXO provides general liability for off-site locations. It also provides additional insured certificates to municipal park boards, which cities often require before approving a booking. Owners running an outdoor program must ensure they have off-site coverage before scheduling any class off-site.

Scenario 7:
Malicious Cyber Attack on Auto-Billing System

A ransomware attack encrypts the studio’s payment gateway and exposes member credit card data. NEXO activates cyber liability coverage to pay for forensic IT investigation, required member notification costs, and crisis management support. The fallout from a breach like this can reach well beyond the technical fix. That is why notification and crisis management costs are built into the coverage.

Facility Operations & Specialized Subfloor Risk Management

The physical build-out of a fitness facility creates risks that commercial buildings may never face. These risks start with the flooring system and extend through rigging, air quality, and sanitation. Addressing these details reduces both how often claims happen and how severe they become.

Facility risk management is not a one-time setup task. It takes ongoing inspection and records because equipment wear and environmental conditions change over months and years of daily use.

Rubber Impact Flooring, Subfloor Hardness & Sound Attenuation

Rubber impact flooring absorbs the force from dropped weights and high-impact movement. It protects both the subfloor and the joints of members training on it. Poorly cushioned subflooring adds stress to ankles and knees. It also transmits noise into the floors below, which can trigger complaints from neighboring tenants or landlord disputes. The Occupational Safety and Health Administration publishes general guidance on workplace floor-surface safety that also applies to commercial fitness spaces.

Choose the right flooring thickness for a specific activity, whether it is Olympic lifting or bodyweight circuit training. This is worth deciding with input from a flooring contractor and an insurance agent. The wrong flooring choice can quietly raise both injury risk and property damage exposure.

Free Weight Drop Zones & Olympic Lifting Platforms

For safety, free weight areas require structural floor load limits, well-specified bumper plates, and a clear safety zone around a lifting platform. Not only does dropping loaded barbells stress the flooring surface, but it also stresses the building structure itself, over and over. This matters even more for older buildings or upper-floor studio spaces. Clear perimeter clearances reduce the likelihood of a bystander getting hit by a dropped plate or rolling barbell.

Write down platform specifications and load limits as part of your standard procedures. This record serves as useful proof of reasonable care if a claim is ever filed for a lifting-area incident.

Cable Rigging, Suspension Trainers & Anchor Point Inspections

Ceiling rigs, suspension trainers, gymnastic rings, and wall anchors are subject to wear and tear with repeated use. That wear is not visible until a failure happens. Monthly inspections that record the condition of every anchor point and cable connection provide facilities with an early warning system before a serious failure occurs. Keep a written record of these inspections, including the date and the name of the person conducting the inspection.

Manufacturers usually publish weight limits and inspection plans for rigging gear. Follow these closely to lower your risk. Many rigging claims trace back to a skipped inspection.

HVAC Air Turnover, Humidity Control & Mold Prevention

Hard training in fitness facilities creates a lot of humidity and dust from sweat, chalk, and heavy breathing. HVAC systems need enough airflow and filtering to manage this. Depending on the facility and HVAC system, higher-efficiency filtration may help improve air quality and reduce airborne dust. This reduces breathing irritation and slip hazards from condensation. The lack of humidity control also allows mold to grow, especially in locker rooms and showers.

Pay special attention to chalk dust control in strength-dominated facilities. Heavy dust build-up affects air quality and equipment life. Instead of a generic commercial building plan, develop HVAC maintenance plans around these fitness-specific conditions

Equipment Sanitation Protocols & MRSA Infection Control

Mats, kettlebells, benches, and other shared gear may spread staph and MRSA from person to person if not cleaned regularly. The Centers for Disease Control and Prevention has released guidelines on preventing the spread of MRSA in shared gym spaces. Clean high-touch equipment on a regular schedule. This minimizes your liability and health risk should there be an outbreak.

Documented cleaning logs have two functions. They protect members’ health and create a paper trail to demonstrate reasonable care should health-related claims be made. Treat sanitation logging the same way you’d treat safety equipment checks.
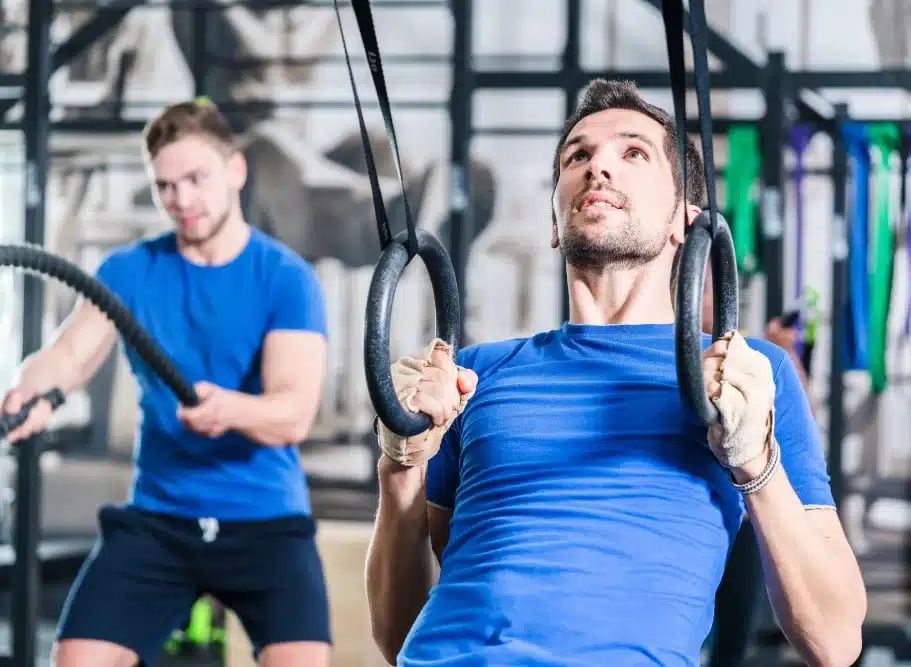
Modality-Specific Risk Profiles & Class Safety

Every fitness format comes with its own risk profile, and general safety plans often overlook what’s specific to each. This gym insurance modality breakdown covers those differences so owners can shape safety practices around their specific environment.

Functional Fitness & High-Intensity Interval Training (HIIT)

Functional fitness and CrossFit-style HIIT classes combine rapid fatigue, high-rep barbell moves, and fast transitions between equipment stations. Fatigue plays a huge part in injuries in this format. Form tends to fall apart during the final rounds of a workout. The transition between pieces of equipment also poses a collision risk when several members are moving between stations at once under time pressure.

Coach your trainers to scale movements as fatigue sets in, rather than letting members go full intensity with bad form. Clearly communicating scaling options reduces injury risk, without changing the overall structure of the class.

24/7 Unstaffed Gym Access & Keycard Security

Facilities that open around the clock with no staff face safety issues that staffed gyms do not. This access model needs a few baseline tools. These are automated AED units, panic buttons, HD cameras, and entry rules that stop tailgating. No staff member is there to respond to an emergency. The facility’s automated systems carry the full weight of that response.

Insurers look closely at these safety systems when underwriting an unstaffed facility, as it significantly changes the risk calculation. Owners considering a 24/7 model should build out these systems before opening, rather than treating them as a later upgrade.

Martial Arts, Combat Sports & Sparring Safety

The risks of martial arts and combat sports are different from those of a strength or cardio class. The main purpose of the activity is contact. Active monitoring during sparring and required gear rules are part of basic safety procedures. Many gym insurance policies don’t cover this category at all. Facilities that run these kinds of programs need coverage built for direct physical contact between members.

Document sparring protocols, including weight or skill-level matching between partners. This can reduce both the frequency of injuries and their severity. Train instructors to step in immediately when a sparring session goes beyond controlled contact.

Pilates Reformers, Aerial Yoga & Hanging Equipment

Pilates reformers rely on spring mechanisms that need regular maintenance to prevent sudden failure during use. Aerial yoga depends on load-bearing silk anchor points that need routine inspection. Spotting safety during inversions and transitions matters just as much as equipment maintenance in preventing injury. A failed spring or a compromised anchor point can cause serious injury with very little warning.

Follow manufacturer-recommended maintenance plans for these formats. Keep records of every inspection performed. These records matter for member safety and for showing reasonable care if a claim happens.

Youth Programs, Childcare & Minor Movement Classes

Children’s programs need their own safety rules. That means parent check-in and check-out, staff-to-child ratios, and full background checks for anyone who works with minors. The moves that children learn need to be age-appropriate. An adult plan is often not suitable for a growing body. Kids are a more vulnerable group, and regulators and insurers may look more closely at youth programs.

Staff background checks are non-negotiable for any facility working with children. Keep records of the screening process for every employee and contractor with access to the youth program. This is one of the areas where prevention and insurance coverage work most closely together. Dance studios that also run programs for young students should apply the same screening standard across every instructor.

How NEXO Insurance Services Protects Fitness Facilities

NEXO Insurance Services operates as a specialized program built around the risks fitness facility owners actually face. It doesn’t simply adapt a generic commercial policy to fit the industry after the fact. Here’s a closer look at NEXO’s track record and the specialized programs behind it.

Verified Insurance Capabilities & Scale
  • Founded in 2005, NEXO has worked as a specialized Managing General Agent (MGA) for over two decades. That gives it deep knowledge of the fitness industry’s risks.
  • NEXO has insured over 20,000 fitness professionals and facility owners nationwide. This covers gyms, studios, and independent trainers.
  • NEXO quotes workers’ compensation coverage in 46 states. This pairs well with payroll tax filing to reduce paperwork for owners.
  • For active policyholders, NEXO issues Certificates of Insurance (COI) and Additional Insured endorsements the same business day.
Background Checks & Specialized Risk Programs

NEXO offers employee background checks at $19.50 per candidate. This gives owners an affordable way to verify compliance with hiring requirements before staff starts working directly with members. The company also built custom property insurance coverage directly for gym assets, including rubber flooring and specialized cardio and strength equipment that generic commercial policies often undervalue.

For independent trainers and movement instructors, NEXO offers an Alternative Balance Program starting at $269 a year. This program includes $2 million per occurrence and $4 million total in liability limits. It also includes $25,000 in per-accident medical expense coverage. Abuse and molestation coverage runs $189, and cyber liability runs $149. This gives independent professionals access to coverage levels that would otherwise need a much larger facility policy.

10-Step Gym Safety & Risk Mitigation Checklist

Turning this guide into daily practice starts with the ten steps below. You can walk through them with your management team and use them as a working baseline for your facility’s risk routine.

1. Verify Member Waiver Execution

Get a digital waiver signed by every active member and guest. Do this before their first workout.

2. Implement Staff Background Checks

Run comprehensive background checks on all employees and contractors. NEXO offers this at $19.50 per check.

3. Inspect Cable Rigging & Anchors Monthly

Check the load rating on all overhead rigs, cables, and straps each month. Write down what you find.

4. Enforce Subfloor Impact Standards

Install rubber flooring in weight drop zones. Choose flooring thickness appropriate for your training environment and equipment, following manufacturer recommendations and building requirements.

5. Maintain Automated External Defibrillators (AED)

Install AEDs where staff can reach them fast. Make sure all floor staff hold active CPR and AED certification.

6. Secure Additional Insured COIs for Landlords

Issue additional insured certificates to your property owner. Do this before your lease starts.

7. Audit Off-Site Event Coverage

Confirm participant liability covers park workouts, outdoor events, and road races.

8. Establish Daily Sanitation Protocols

Keep written cleaning logs for mats, showers, and shared cardio equipment.

9. Implement 24/7 Camera Monitoring

For unstaffed facilities, maintain a rolling 90-day archive of HD video covering all floor areas.

10. Review Insurance Coverage Annually

Update your payroll, equipment values, and member counts with NEXO each year.

Frequently Asked Questions

Premiums vary significantly based on state, revenue, payroll, claims history, services offered, and coverage limits. Your rate depends on factors such as square footage, revenue, payroll, member volume, and any high-risk equipment on-site. NEXO builds a quote around your facility's actual risk profile rather than a flat industry rate.

Active policyholders can request a Certificate of Insurance (COI), including Additional Insured endorsements for landlords or venue managers, and NEXO turns these around the same business day. New policy applications are usually quoted within one business day.

Yes, and this is a gap many owners miss. General liability policies frequently exclude independent contractors altogether. You have two options: require each 1099 trainer to carry their own liability policy naming the gym as an additional insured, or extend contractor coverage through your facility's own policy. NEXO offers instructor coverage starting at $269 a year.

Not automatically. It depends on whether the policy includes participant injury coverage as part of the base plan. Many standard general liability policies carry an athletic exclusion that removes this protection entirely. NEXO builds participant liability insurance into its base policy from the start, so injuries that happen during active training are already covered.

Your property and general liability coverage keeps running in the background, protecting the space against break-ins, water damage, or slip-and-fall incidents, even when the doors are closed. What can change is your workers' compensation reporting, since payroll-based premiums can be adjusted to match reduced seasonal staffing. It's worth reaching out to NEXO ahead of any planned closure to ensure your payroll estimates reflect reality.

It can, as long as the leased equipment is listed on your policy at its full replacement value. Many leasing companies may also ask for a Certificate of Insurance naming them as a loss payee and an additional insured. NEXO builds property endorsements specifically for leased fitness equipment, so this is a straightforward add rather than an afterthought.

Often, no. Generic commercial property policies tend to lump flooring and mirrors in with standard tenant improvements, which can leave you underinsured if something happens. NEXO takes a different approach, writing property coverage around what a fitness facility actually contains, including rubber impact flooring, subfloors, wall mirrors, and sound systems.

An unstaffed, round-the-clock facility needs more than a standard policy. You're looking at general liability with an unstaffed facility endorsement, commercial property coverage, cyber liability, and a set of physical safeguards like HD surveillance, panic buttons, and automated AEDs. NEXO writes coverage designed specifically for this access model rather than treating it as an edge case.

Often, yes. Many off-site programs require coverage that specifically extends beyond your primary facility. Many local park departments may also require a Certificate of Insurance naming the city as an additional insured before they'll approve the booking. NEXO includes off-site coverage in its base policies and can issue those municipal certificates without extra hassle.

NEXO can quote workers' compensation in 46 states. The four exceptions are Hawaii, North Dakota, Ohio, and Wyoming, each of which operates its own monopolistic or specialized state fund rather than allowing private carriers to write this coverage.

This is worth a direct conversation with your agent before you finalize a sale or closure, since the right answer depends on your specific policy structure. The risk with a claims-made policy is that coverage applies only while the policy remains active. If it lapses after a sale, older claims could end up with no coverage. NEXO helps owners work through this timing so a change in business status doesn't quietly create a gap.

Business interruption coverage is built for exactly this. It replaces lost income, payroll, and rent obligations while your facility is out of commission for a covered reason. The payout is based on your past auto-draft revenue and the fixed costs you're still incurring during the repair window, such as rent and utilities. NEXO handles this alongside the property claim itself, so the repair and the lost income are addressed as a single process.

This coverage protects your business if an employee or contractor is accused of improper conduct toward a member or client. It's not legally required everywhere, but it's strongly recommended for any facility that runs youth classes, gymnastics, or childcare. NEXO pairs this coverage with background checks at $19.50 per candidate, giving owners a practical way to stay ahead of hiring risk.

Usually not. Combat sports and contact sparring fall outside the scope of a standard gym policy. Martial arts facilities need coverage designed around direct participant contact, which is a different risk category than a typical strength or cardio class. NEXO offers programs built specifically for martial arts and combat sports.

If your billing software or member database is breached, cyber liability insurance covers the cleanup. That includes forensic investigation, data recovery, regulatory fines, and the cost of notifying affected members, which state data breach laws often require within tight timelines. These costs escalate quickly once notification requirements kick in.

Yes, and it's worth considering if your equipment is connected or software-driven. Equipment breakdown coverage protects against sudden mechanical or electrical failure, power surges, and computer logic issues, none of which are typically covered under a standard fire and water property policy. As more gyms adopt smart equipment, this gap becomes increasingly relevant.

A waiver isn't a substitute for liability insurance, but a properly executed one still matters. It establishes that the member understood and accepted the risk, which strengthens your position if a claim is filed. NEXO expects policyholders to keep active waiver records and can guide you through setting up a digital waiver process.

Protect Your Facility with NEXO Insurance Services

The coverage descriptions in this guide explain how each insurance line usually works for gym and fitness studio owners. What any single policy actually covers depends on its specific terms, limits, and exclusions. Review your own policy documents with a licensed agent to confirm exact protection for your facility.

Gym and fitness studio insurance is not one single product. It is a mix of coverages built around how a facility actually runs day-to-day. This ranges from participant liability during a group class to cyber protection for an auto-billing system. Each policy line covers a risk that a generic business policy often misses. Owners who understand these coverages and pair them with the safety steps above are often in a much stronger spot when an incident happens.

Ready to secure comprehensive liability, property, and workers’ compensation coverage built for your gym or fitness studio? Contact NEXO Insurance Services today for a custom quote.

NEXO Insurance Services

Phone: (310) 937-2007

Website: https://nexofit.com/

Office Location: Manhattan Beach, California

This guide provides general information and is not legal or insurance advice. Coverage varies by policy, carrier, and jurisdiction. Review your specific policy documents with a licensed agent, and have liability waivers and employment classifications reviewed by qualified legal counsel.

×

Answer two questions to get an instant quote.

$